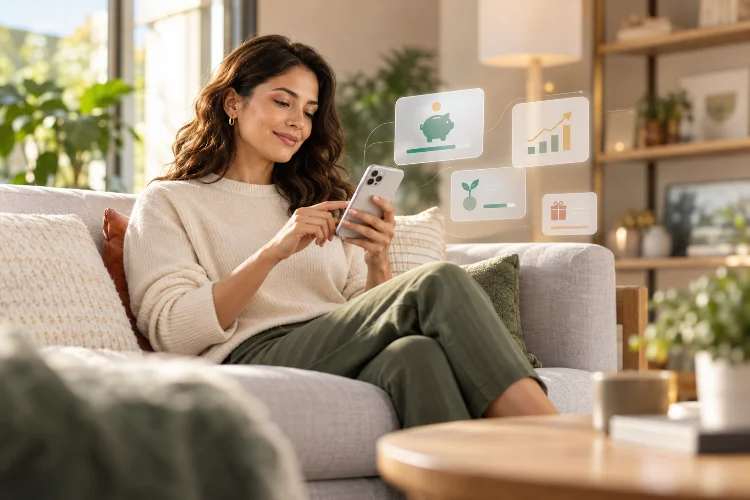
Imagine opening your banking app and immediately seeing a savings recommendation that actually makes sense for your financial situation.
Not a random credit card promotion. Not another generic advertisement. Just a helpful suggestion based on your spending habits, financial goals, and personal preferences.
Pretty refreshing, right?
Now imagine receiving that same level of attention whenever you contact customer support, apply for a loan, or explore new banking products.
That’s exactly what modern consumers are beginning to expect from their financial institutions.
Personalized banking services are changing how banks build relationships, improve customer satisfaction, and encourage long-term loyalty.
Instead of treating every account holder the same way, financial institutions can use customer insights, artificial intelligence, and behavioral analytics to create more relevant financial experiences.
And this matters more than ever.
Customers can easily compare banking products, explore digital alternatives, and move their financial activities between providers.
For banks, delivering competitive interest rates is no longer enough to guarantee loyalty.
The real opportunity lies in making customers feel understood, supported, and genuinely valued.
Let’s explore how personalization transforms banking relationships and why it has become such an important strategy for improving customer retention.
1. Why Customer Retention Is Becoming a Major Banking Challenge
Keeping existing customers engaged has become increasingly complicated.
Years ago, many people maintained the same banking relationship for decades, often because switching providers involved paperwork, inconvenience, and limited alternatives.
Today, digital banking has changed that dynamic.
Customers can open accounts remotely, compare financial products online, and manage money through multiple banking applications.
Banking Loyalty Is No Longer Guaranteed
According to Accenture’s Banking Consumer Study 2025, which examined 49,300 customers across 39 countries, 73% of surveyed consumers engaged with multiple banks beyond their primary institution.
The same study found that 58% had purchased a financial product or service from a new provider within the previous twelve months.
These findings reveal an important distinction.
Customers don’t necessarily need to close their primary account to become less loyal.
They might keep their existing bank while gradually moving savings, investments, credit card spending, or loan relationships elsewhere.
This creates a serious challenge for traditional customer retention strategies.
Why Personalization Changes the Relationship
When banking experiences feel generic, customers often compare providers primarily through fees, interest rates, and convenience.
But when a bank understands individual needs, the relationship becomes more meaningful.
For example, a customer saving for their first home might appreciate practical budgeting insights and mortgage guidance.
Someone managing a small business may value cash flow forecasting and flexible payment solutions.
These experiences create reasons to remain engaged beyond basic transaction processing.
Personalization won’t prevent every customer from switching, but it can strengthen perceived value and make an institution more useful in everyday financial life.
That’s the foundation of sustainable banking loyalty.
2. Using Customer Data to Understand Individual Financial Needs
Personalized banking begins with understanding customers.
Financial institutions already process enormous amounts of information through transactions, account activity, customer interactions, and product usage.
However, collecting data isn’t the same as turning it into something useful.
The real challenge is identifying insights that improve customer experiences without compromising privacy.
Building a Complete Customer View
Many banks maintain customer information across seperate systems.
Savings accounts, lending platforms, mobile applications, and customer service departments may each hold different pieces of information.
When these systems don’t communicate effectively, employees struggle to understand the customer’s complete relationship with the bank.
A connected customer data platform can help organize permitted information into a more consistent view.
For example, a customer service representative might see that someone recently applied for a mortgage, contacted support about documentation, and scheduled a consultation.
Instead of asking the customer to explain everything again, the representative can continue the conversation with appropriate context.
This reduces frustration and improves service continuity.
Turning Behavioral Insights Into Useful Services
Advanced analytics allows banks to recognize spending patterns and changing financial needs.
Imagine a customer who consistently spends more than usual during certain months.
A banking application could provide a budgeting reminder or suggest setting aside additional savings beforehand.
Another customer receiving a salary increase might appreciate information about improving their emergency fund or reviewing existing financial goals.
These suggestions should be helpful rather than intrusive.
Banks must avoid making inappropriate assumptions about personal circumstances or pushing unsuitable financial products.
The objective is to use reliable information to make services more relevent, convenient, and valuable.
When customers repeatedly receive useful insights, they have more reasons to continue using the bank’s digital services.
3. Delivering the Right Financial Products at the Right Time
Nobody enjoys receiving endless financial promotions that have absolutely nothing to do with their needs.
A student probably doesn’t need repeated offers for premium business banking services.
Similarly, an established business owner might find beginner-focused financial products completely irrelevant.
Modern banking personalization attempts to solve this problem through more targeted communication.
Moving Beyond Generic Product Recommendations
Traditional banking campaigns often group customers into broad categories based on age, income, or account type.
While these characteristics can provide context, they rarely explain someone’s complete financial situation.
Advanced customer analytics can help institutions identify more specific needs using appropriate, authorized information.
For example, someone regularly maintaining a growing savings balance might receive information about alternative deposit products.
A customer approaching the end of a fixed-rate mortgage could receive a timely reminder about upcoming refinancing considerations.
The key is timing.
A useful recommendation delivered when customers actually need it feels very different from an aggressive sales message.
Supporting Important Financial Life Stages
Financial priorities change throughout life.
Someone beginning their first job may focus on everyday expenses and emergency savings.
A few years later, that same person might become interested in homeownership, family financial planning, or long-term investments.
Banks that recognize these transitions can provide more meaningful assistance.
Consider a young professional who recently started saving consistently.
Instead of immediately promoting a complicated investment product, the bank might offer educational content explaining savings goals, financial risk, and available options.
As the customer’s needs develop, services can evolve accordingly.
This approach builds relationships around financial progress rather than one-time transactions.
It also supports responsible cross-selling by focusing on customer suitability.
The strongest personalization strategies help people make better decisions instead of simply encouraging them to purchase more products.
4. Creating Seamless Omnichannel Banking Experiences
Personalization shouldn’t disappear when customers move between banking channels.
Imagine explaining a payment problem through mobile chat, calling customer support afterward, and discovering that the representative knows nothing about the earlier conversation.
That’s frustrating.
Unfortunately, disconnected service experiences remain a challenge for many financial institutions.
Connecting Mobile, Online, and Branch Banking
Omnichannel banking aims to create consistent customer experiences across digital applications, websites, contact centers, and physical branches.
The goal is simple: customers should be able to continue their banking activities without repeatedly starting from the beginning.
For example, someone might begin a personal loan application through a mobile device.
Later, they could visit a branch to discuss repayment options with a financial advisor.
With integrated systems and appropriate permissions, the advisor could access the customer’s application progress and help complete the process.
This makes the experience feel connected instead of fragmented.
Capgemini’s World Retail Banking Report 2025 found that 86% of surveyed banking executives planned to prioritize omnichannel experiences over the following twelve months.
The finding reflects how important connected customer journeys have become.
Combining Digital Convenience With Human Support
Artificial intelligence and automation can improve responsiveness, especially for routine banking inquiries.
However, not every financial conversation should be handled entirely by software.
Customers dealing with suspected fraud, serious financial difficulties, or complicated lending decisions may need empathetic human assistance.
A personalized banking strategy should recognize these differences.
For straightforward questions, customers might prefer an intelligent virtual assistant that provides immediate answers.
For sensitive situations, the system should make it easy to reach a qualified employee who understands the relevant context.
Offering both options improves flexibility.
Customers feel more confident when they know their bank can provide fast digital solutions without removing access to human expertise.
5. Strengthening Customer Loyalty With Personalized Rewards
Loyalty programs have existed in banking for years.
Credit card points, cashback offers, fee discounts, and exclusive benefits are familiar strategies for encouraging customer engagement.
However, traditional rewards programs often struggle because they provide similar incentives to everyone.
Personalization offers a more interesting alternative.
Why Generic Banking Rewards Often Underperform
Capgemini’s Driving Loyalty With Experience report, drawing on its 2025 retail banking research, found that 73% of surveyed customers considered rewards programs insufficiently personalized.
The research also found that 47% of card customers believed the value they received wasn’t worth the associated fees.
These numbers highlight an important problem.
A reward doesn’t automatically create loyalty simply because it has financial value.
Customers must actually consider that reward useful.
Someone who rarely travels probably won’t be particularly impressed by airport lounge benefits.
A customer who frequently purchases groceries might prefer cashback for everyday household spending.
The same reward can feel valuable to one person and completely irrelevant to another.
Designing Rewards Around Customer Preferences
Banks can improve loyalty programs by offering benefits that reflect individual preferences.
For example, a customer might choose between cashback categories, travel-related benefits, or discounts on selected everyday expenses.
Another approach involves adapting reward recommendations based on eligible transaction categories and preferences expressed by customers.
This creates a sense of control.
Instead of forcing everyone into a standardized program, banks allow customers to select benefits that fit their lifestyles.
Personalized rewards can also encourage continued account activity.
A customer who regularly receives useful benefits may have stronger reasons to use the same payment card or banking application.
However, banks should ensure that reward conditions remain understandable.
Complicated redemption requirements and unexpected restrictions can quickly undermine trust.
The best loyalty programs combine meaningful incentives with simplicity, transparency, and genuine customer value.
6. Building Trust Through Responsible Personalization and Data Privacy
Personalization depends on information, but financial data is exceptionally sensitive.
Customers may appreciate helpful spending recommendations while feeling uncomfortable about how much their bank knows about them.
This creates a delicate balance.
Banks need enough information to deliver useful experiences without making customers feel constantly monitored.
Transparency Makes Personalization More Acceptable
Imagine receiving a notification that seems to know something unusually specific about your financial situation.
Even if the recommendation is accurate, you might wonder how the institution obtained that information.
Clear communication helps prevent this reaction.
Banks should explain what information they collect, why they use it, and which choices customers have regarding personalization.
Relevant consent and preference controls should be easy to understand.
Customers should also be able to adjust optional notifications and marketing preferences without navigating complicated settings.
Deloitte’s August 2026 research, based on a survey of almost 2,600 US banking customers, found that 72% were concerned about sharing financial information with generative AI tools.
Although the finding focuses on generative AI, it reinforces the importance of data confidence when developing intelligent financial experiences.
Avoiding Intrusive or Unfair Recommendations
Just because technology can predict customer behavior doesn’t mean banks should act on every prediction.
For example, identifying financial vulnerability shouldn’t become an opportunity to promote unsuitable borrowing products.
Responsible personalization requires boundaries.
Financial institutions should evaluate recommendations for fairness, accuracy, customer suitability, and potential harm.
Security measures, data minimization, access restrictions, and regular system reviews also help protect sensitive information.
A 2024 report from the US Consumer Financial Protection Bureau examined consumer privacy protections and potential gaps involving the commercial use of financial data.
The broader lesson is that personalization needs to respect customer rights and applicable privacy requirements.
Trust develops when people feel their information is being handled responsibly.
And trust remains one of the strongest foundations for long-term banking relationships.
7. Measuring the Impact of Personalization on Customer Retention
Introducing personalized recommendations doesn’t automatically mean a bank has improved customer loyalty.
Financial institutions need measurable evidence that their strategies are delivering meaningful results.
That requires looking beyond digital engagement metrics alone.
Tracking Customer Retention and Engagement
One important measurement is the customer retention rate.
A simplified calculation compares the number of customers remaining at the end of a period, excluding newly acquired customers, with the customer base at the beginning.
Other useful indicators include account activity, product engagement, satisfaction levels, complaint resolution, and customer lifetime value.
Consider a hypothetical bank beginning the year with 10,000 customers.
If 8,500 existing customers remain at year-end, its annual retention rate is 85%.
Now imagine that better service experiences help improve retention to 88%.
That represents 300 additional existing customers retained, assuming the starting population and measurement approach remain comparable.
The example is illustrative, but it shows why even modest improvements can matter commercially.
Testing Which Experiences Actually Work
Banks should evaluate personalization initiatives using controlled experiments whenever practical.
For example, a financial institution could test two customer onboarding experiences.
One group receives standard welcome communications, while another receives tailored educational content and relevant account setup guidance.
After an appropriate observation period, the bank can compare product activation, satisfaction, engagement, and retention outcomes.
This provides stronger evidence than simply assuming that more personalized communication produces better results.
Management should also consider implementation expenses and potential negative consequences.
An AI recommendation system might increase engagement but become financially unattractive if operating costs exceed its benefits.
Successful programs need consistant measurement and regular refinement.
Creating a Long-Term Personalization Roadmap
Banks don’t need to personalize every customer interaction immediately.
A practical strategy starts with a few high-impact experiences, such as onboarding, financial goal tracking, customer support, or card rewards.
Teams can then evaluate customer feedback and operational performance before expanding the program.
Cross-functional cooperation is essential.
Technology specialists, customer experience teams, compliance professionals, and financial product managers need to work toward shared objectives.
McKinsey’s Global Banking Annual Review 2025 emphasizes that customers are becoming more deliberate about choosing financial providers.
Its analysis also shows that being a customer’s primary bank creates a meaningful advantage when competing for additional product relationships.
For banking leaders, that reinforces an important principle.
Retention isn’t simply about preventing account closures. It’s about remaining a trusted and valuable part of customers’ financial lives.
Institutions that understand this can build stronger relationships while supporting sustainable business growth.
Personalized banking services are changing how financial institutions attract, engage, and retain customers.
By combining customer insights, relevant financial recommendations, connected service channels, and meaningful loyalty benefits, banks can create experiences that encourage stronger long-term relationships.
However, effective personalization requires more than advanced technology.
Financial institutions must also protect sensitive information, respect customer preferences, maintain transparency, and measure results against clear business objectives.
The goal isn’t overwhelming customers with customized promotions. It’s making banking simpler, more helpful, and more relevant to their everyday financial needs.
Banks that deliver this value consistently have a better opportunity to earn lasting customer trust and loyalty.
Ready to strengthen your banking customer retention strategy? Start by identifying customer frustrations, improving your data-driven services, and developing personalized experiences that create genuine financial value.